
During the ongoing disinflation process in Türkiye, rents have continued to exhibit considerable rigidity. One factor contributing to this persistence was the loss of housing stock following the February 6, 2023 earthquakes, compounded by migration from the earthquake zone to other provinces. In the subsequent period, however, housing supply in the earthquake zone recovered rapidly, supported by government-led reconstruction efforts. To what extent has this recovery in housing supply translated into regional rent dynamics? In this blog post, we examine developments in housing supply and regional rental prices in the aftermath of the earthquakes to shed light on this question.
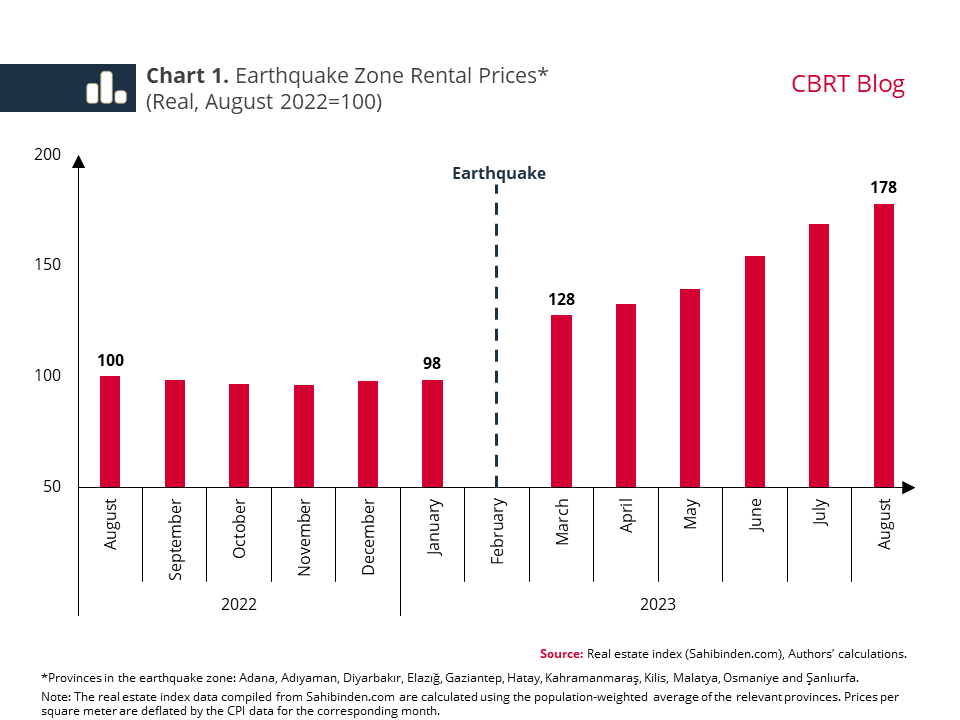
Following the February 6 earthquakes, and the decline in housing stock in the earthquake zone, rental housing prices in the region rose rapidly (Chart 1). The impact of the earthquakes on the rental market was not confined to the earthquake zone. Post-earthquake migration flows drove up demand for rental housing and rental prices in provinces receiving migrants. Akgündüz and Kayrıcı (2026) show that this indirect effect of the earthquake varied across provinces. According to their paper, rents in provinces located near the earthquake zone and/or those with strong regional migration ties to it increased significantly.
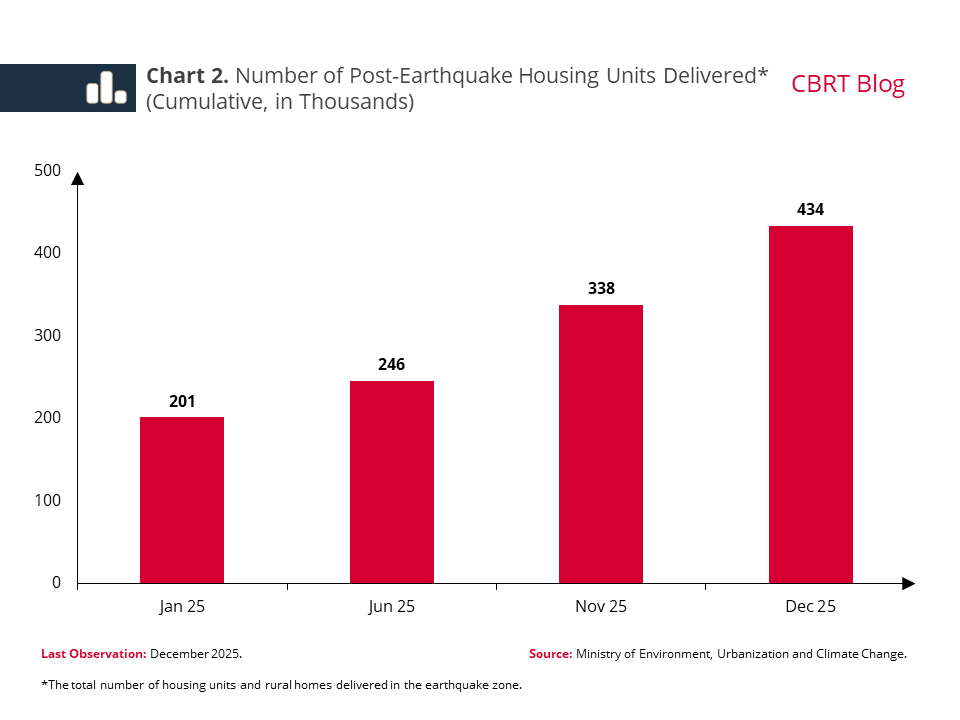
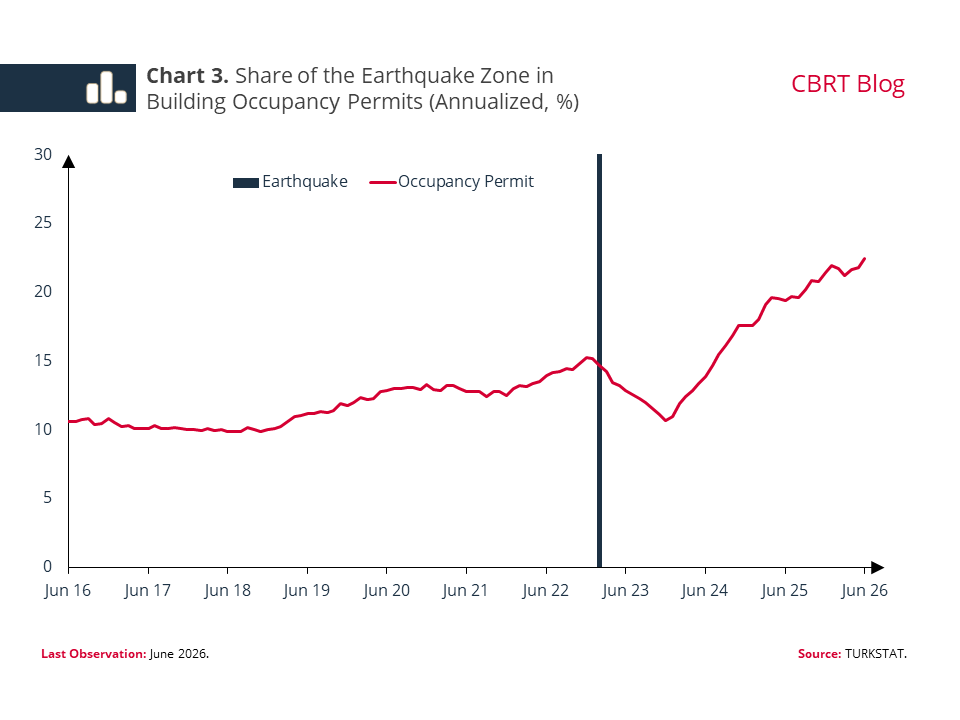
To compensate for the loss incurred in housing supply caused by the earthquake, a comprehensive government-led reconstruction process began in the region. The number of housing units built by TOKI (Housing Development Administration of Türkiye) in the earthquake zone following the earthquakes reached 201,000 at the beginning of 2025 and approximately 434,000 by the end of the year (Chart 2). Compared to the number of housing units TOKI built nationwide in the three years prior to the earthquakes (approximately 213,000), this figure indicates a significant increase in housing supply. The recovery in housing supply is also clearly visible in building occupancy permits (Chart 3). Before the earthquake, the earthquake zone accounted for around 12% of building occupancy permits issued across Türkiye on average, while this share rose to over 20% in 2025.
Following such a substantial increase in housing supply, the key question is the extent to which this development has been reflected in rental market dynamics. To answer this question, we examine the provinces in three groups, drawing on Akgündüz and Kayrıcı (2026): provinces in the earthquake zone, provinces where rental prices were indirectly affected by the earthquake, and other provinces.[1] A comparison based on online rental listing prices reveals a striking pattern. While rent inflation in the earthquake zone was significantly higher than in the other two groups in 2023 and 2024, it began to slow in 2025 as housing deliveries accelerated (Chart 4). In other words, we observe that the acceleration in rent increases due to the loss in housing supply in the post-earthquake period has relatively lost momentum as housing supply has rebounded.
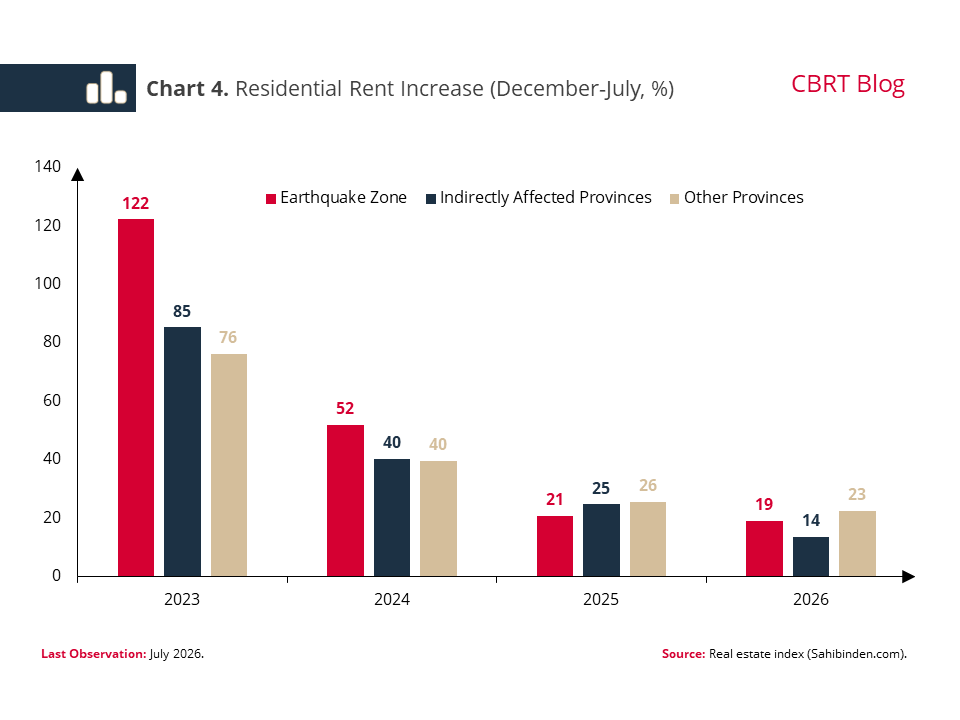
Strikingly, this divergence is not limited to the earthquake zone. In the indirectly affected provinces, rent inflation in 2024 and 2025 was close to that in other provinces, but in 2026, it is significantly lower. This suggests that the recovery in housing supply in the earthquake zone may also be gradually curbing the rental housing demand in provinces that have previously received migration, doing so through the reverse migration channel. The delivery of housing units and the households’ decisions to return do not overlap due to various family preferences and constraints, which could explain why this effect appears with a lag.
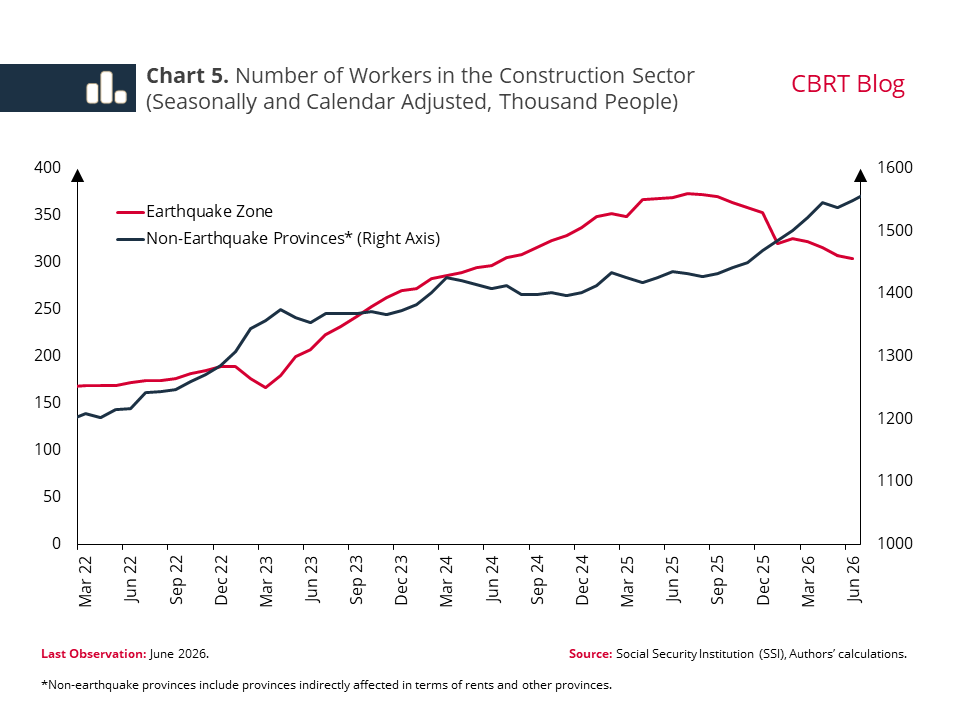
How, then, might this effect evolve in the period ahead? Here, the regional distribution of construction activities serves as a significant indicator. While the construction employment has declined in the earthquake zone following the completion of post-earthquake housing projects to a large extent, it has increased sharply in non-earthquake provinces (Chart 5). The construction capacity has been shifting outside the region, which indicates that the rise in housing supply may spread across a wider geographic area in the period ahead. Also considering that the reverse migration process is taking some time, the impact of the post-earthquake reconstruction process on rent dynamics may extend beyond the delivery of housing units. In this respect, the rise in housing supply in the earthquake zone seems likely to keep holding down rent increases both in the earthquake zone and in the indirectly affected provinces.
To sum up, the post-earthquake decline in the housing stock had an adverse impact on rent inflation in the earthquake zone as well as in a number of other provinces due to migration flows. However, we see that the rent inflation in the earthquake zone has slowed significantly amid the sharp increase in housing supply owing to the government-led reconstruction activities, and this slowdown has become visible in the indirectly affected provinces as well in 2026. The fact that the construction sector capacity has been shifting from the earthquake zone to non-earthquake provinces indicates that the rise in housing supply may spread across a wider area. Against this background, the improvement in housing supply will be among the factors that can support the slowdown in rent inflation in the period ahead.
[1] The indirectly affected provinces are Ankara, Antalya, Aydın, Batman, Bursa, Karaman, Kayseri, Konya, Manisa, Mardin, Mersin, Muğla, Niğde, Sivas and Van.